Before gold reopens: separate the first quote from the first useful evidence
Sunday preparation after the 13 November New York session: preserve Friday’s gold reference, distinguish stale dollar data and define what would make the reopening informative.
New York session reviewed: 2026-11-13
Published
Editorial cutoff · Gabriel Nicolaev — CyGuru
The five-question brief
What happened?
Friday, 13 November remains the last completed New York session. Sunday is the publication date, not a newly completed trading session. December futures settled at $3,886.30 according to Reuters.
What explains it?
The article below separates verified releases from conditional interpretations. A headline alone does not establish the cause of a price move.
What is still missing?
Final spot close, verified intraday OHLC, executable reopening prices and synchronized gold/dollar/yield observations are unavailable. No broker fills, costs, P&L or signal outcomes are claimed.
What could change the reading?
Contradictory observations over matching timestamps, revised source data or failed follow-through can weaken an interpretation. An explanation must be reconsidered when its required evidence is absent.
What will I watch?
Compare the first observations from the same instrument and provider with a saved Friday baseline. Check quote age and spreads before interpreting an opening move; reassess the hypothesis after liquid trading resumes.
Friday, 13 November remains the last completed New York session. Sunday is the publication date, not a newly completed trading session. December futures settled at $3,886.30 according to Reuters.
Friday supplies a reference, not a Sunday market
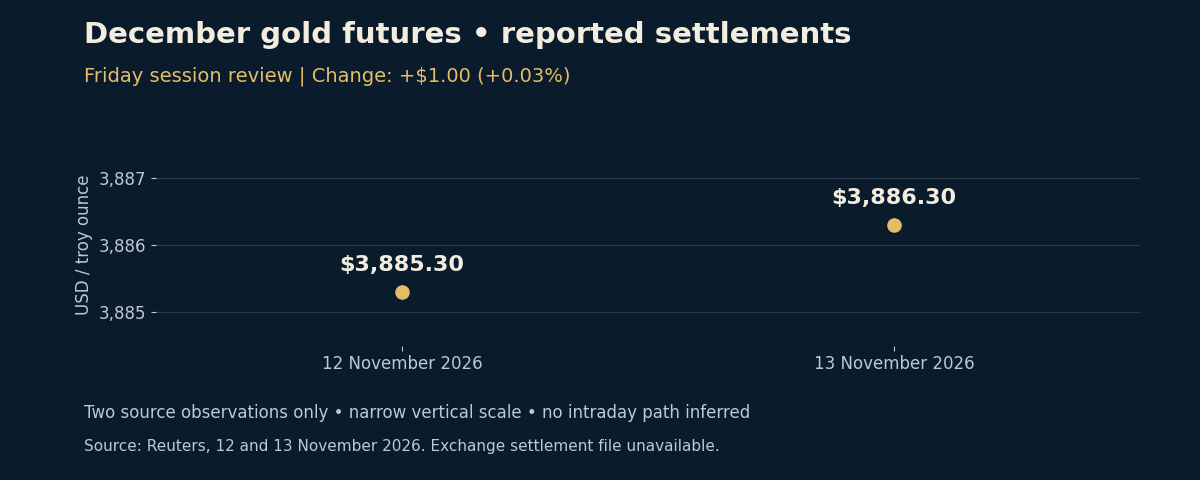
Reuters recorded spot gold at $3,879.71 at 19:05 UTC on 13 November and December futures settling at $3,886.30. Thursday’s settlement for that contract was $3,885.30. These are different instruments and observation conventions; the spot quotation is not a final close. The chart preserves only the two reported futures endpoints. The preparation problem is therefore practical: which exact reference will you use when trading resumes, and will the new observation be comparable?
The first quote needs an information label
My preferred reopening record has four fields before any interpretation: instrument, provider, timestamp and quote status. A displayed weekend value may simply be the last available reading. A newly refreshed interface does not establish a newly traded price. Likewise, an early quotation from one provider need not represent the conditions available elsewhere. An opening move becomes more useful evidence when its timing and tradability are clear. The task is to establish comparability before explaining direction.
The macro baseline remains restrictive, but it is not an order
Treasury’s 13 November ten-year nominal par yield was 5.15%; the real par reference was 2.91%. Both rose five basis points from 12 November. BLS reported October final-demand PPI up 0.3% monthly and 6.5% annually, released Friday at 13:30 UTC. These dated facts frame the next observation. My interpretation is that a gold recovery should be examined alongside the financing backdrop, without requiring every short-term movement to obey an inverse relationship. A macro headwind does not determine the next executable price.
The dollar panel has a deliberate time lag
The Federal Reserve broad dollar series displayed by FRED still ends on 6 November at 121.8803, updated 9 November at 21:16 UTC. Its next listed release is 16 November. This edition does not call that a Friday dollar close. When the series updates, check the dates of the observations supplied rather than treating the release date as their trading date. A differently constructed dollar index may help with timely monitoring, but it should have a separate label and baseline.
Three reopening questions worth writing down
First, does an initial gold move persist after more participants can transact, or does it reverse? Second, do subsequently available currency and yield observations support the same explanation over a matched interval? Third, does genuinely new information alter the starting hypothesis, or are old headlines being recirculated? These are interpretation tests, not buy or sell conditions. Record a competing explanation before reviewing the later chart. That makes it harder to retrofit every outcome to the first story that felt convincing.
What would make the evidence stronger
A recovery accompanied by easing real yields would support a different reading from a recovery despite firmer real yields. Neither alone identifies the marginal buyer. Conversely, gold weakness despite a softer dollar would prompt a search for other explanations, not an automatic assertion of hidden selling. The useful next step is a synchronized observation set with a defined horizon. Keep missing observations blank; do not insert a provider’s last quote merely to make every column look complete.
Preparation includes the choice to wait
Before any live decision, verify the product’s trading hours, order rules and costs with its provider. This brief does not authenticate a reopening schedule or estimate spreads. An attractive opening price is not evidence of an available fill at the intended size. The terminal can organize charts and reported signal histories, while a journal can preserve the reasoning; neither replaces execution records. No new weekend session, signal success or monetary result is inferred here. The separate weekly report studies the curve change across the completed week rather than repeating this reopening checklist.
Sources and observation times
- Reuters via MarketScreener · 13 November, updated 19:34 UTC; spot observation 19:05 UTC ↗
- Reuters · 12 November; December settlement; exact settlement publication minute unspecified ↗
- BLS · October PPI released 13 November at 13:30 UTC / 17:30 Dubai ↗
- U.S. Treasury · nominal par curves, 6–13 November; publication hour unspecified ↗
- U.S. Treasury · real par curves, 6–13 November; publication hour unspecified ↗
- Federal Reserve via FRED · 6 November observation, updated 9 November at 21:16 UTC ↗
Sources checked for this edition at the editorial cutoff above. Provider observation times remain separate from publication time. Linked statistical pages may later display revised data.
Continue the study
Read inflation releases with precision →
Research Lab: study the price record →
Educational editorial analysis, not a trade recommendation. This archived edition does not update with later announcements.